Accounting across Canada
Accounting and Tax Guide for Hamilton Businesses
Hamilton businesses should use stable inventory and job cost categories, so margin changes reflect operations, and book equipment apart from repairs.
By HBT AccountingSources checked 7 min read
Key points
- Hamilton businesses generally manage federal tax and payroll accounts, Ontario corporate rules, and HST administered by the CRA. Inventory, equipment, subcontracting, and employee costs may need additional accounting controls depending on operations.
- Statistics Canada reported 785,184 people in the Hamilton census metropolitan area in the 2021 Census. This is census metropolitan area data, not a municipal population.
- HBT Accounting works from Calgary, Alberta and can discuss suitable remote engagements across Canada. This page does not represent a Hamilton office.
What the official Hamilton data shows
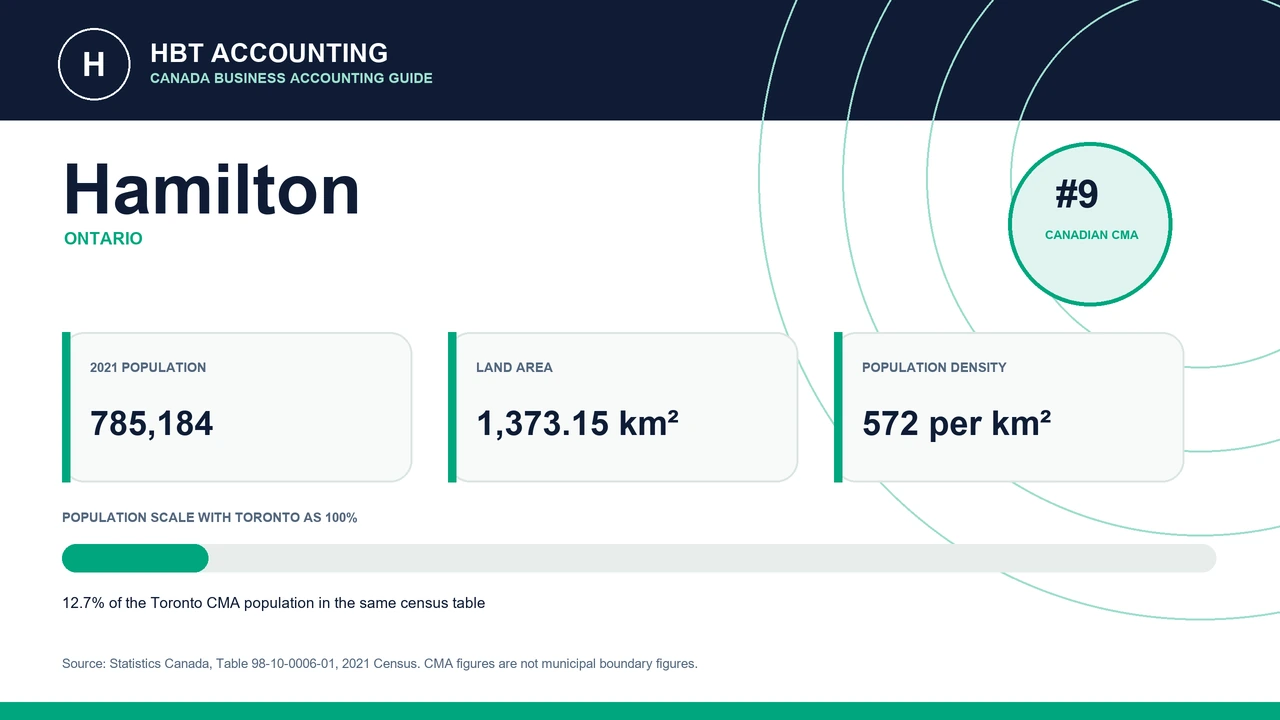
Statistics Canada ranked the Hamilton census metropolitan area number 9 among Canadian census metropolitan areas by 2021 population. The official table reports 785,184 people across 1,373.15 square kilometres. That is about 572 people per square kilometre.
| Measure | Result |
|---|---|
| Population | 785,184 |
| Land area | 1,373.15 km2 |
| Population density | 572 people per km2 |
| National CMA rank | Number 9 |
Build the federal and Ontario reporting map
When materials, labour, and outside services are posted inconsistently, gross margin can move for accounting reasons rather than operating reasons. The records should use stable inventory and job cost categories, record equipment separately from repairs, and capture complete supplier documents. For GST or HST, the applicable rate can depend on the supply and the CRA place of supply rules, not simply the city shown on the invoice. A separate provincial sales tax requires its own current provincial review.
A practical accounting focus for Hamilton
The local example is inventory, job costs, equipment purchases, and payroll that must agree with HST and corporate tax records.
The decision focus is whether margin reports reflect real operating changes and can be traced to source documents.
- Reconcile inventory movement to purchases and sales
- Separate capital equipment from operating expenses
- Match supplier invoices to the correct job
- Review payroll coding for direct and indirect labour
Official sources
Call or email and we will tell you which records we need and what the work costs, in writing, before anything starts.
Important. This article provides general educational information, not legal or tax advice for a specific business. Rules, administrative policies, rates and deadlines can change. Confirm your facts and current obligations with the responsible government agency and a qualified adviser.