Accounting across Canada
Accounting and Tax Guide for Toronto Businesses
Toronto businesses should first separate revenue by channel, reconcile deposits to gross sales and record the province of each material sale for HST.
By HBT AccountingSources checked 7 min read
Key points
- Ontario businesses generally work within the federal income tax and payroll systems, the HST system administered by the CRA, and any Ontario programs that apply to their facts.
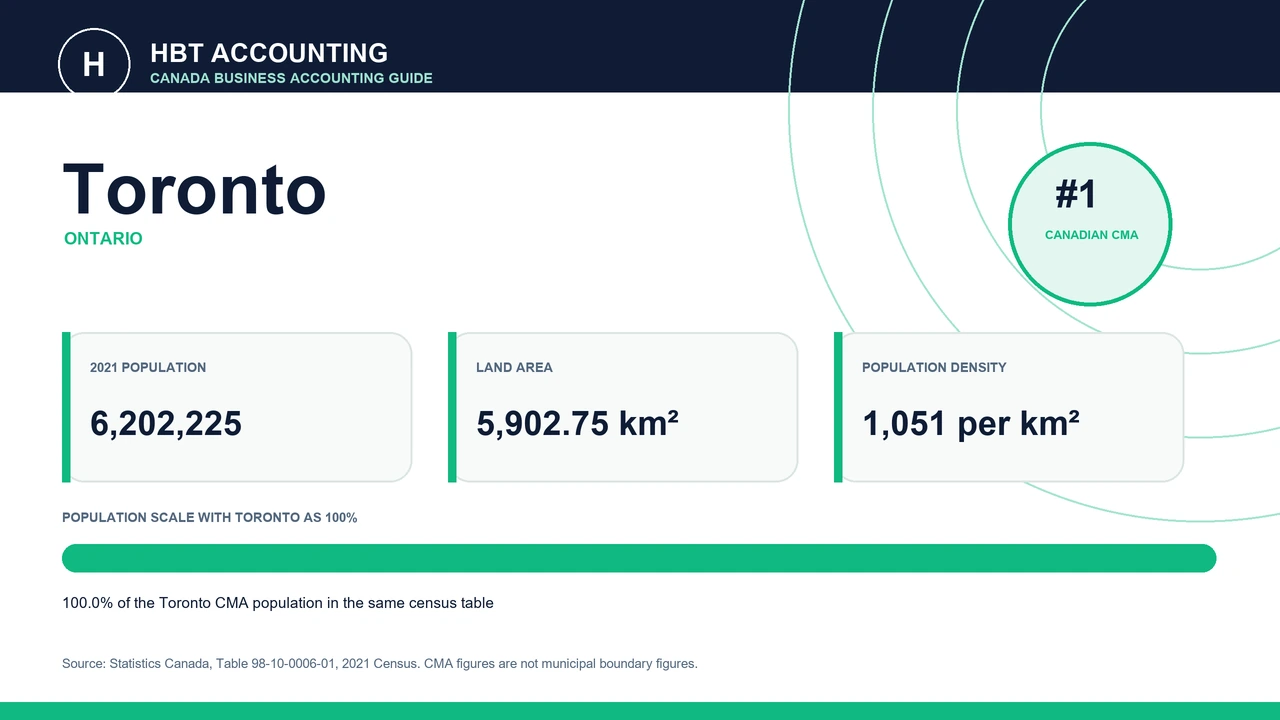
- Statistics Canada reported 6,202,225 people in the Toronto census metropolitan area in the 2021 Census. This is census metropolitan area data, not a municipal population.
- HBT Accounting works from Calgary, Alberta and can discuss suitable remote engagements across Canada. This page does not represent a Toronto office.
What the official Toronto data shows
Statistics Canada ranked the Toronto census metropolitan area number 1 among Canadian census metropolitan areas by 2021 population. The official table reports 6,202,225 people across 5,902.75 square kilometres. That is about 1,051 people per square kilometre.
| Measure | Result |
|---|---|
| Population | 6,202,225 |
| Land area | 5,902.75 km2 |
| Population density | 1,051 people per km2 |
| National CMA rank | Number 1 |
Build the federal and Ontario reporting map
A Toronto company can outgrow an informal spreadsheet quickly when online sales, contractors, employees, and owner transactions are recorded in different places. The records should separate revenue by channel, reconcile merchant deposits to gross sales, and document the province connected with material sales. For GST or HST, the applicable rate can depend on the supply and the CRA place of supply rules, not simply the city shown on the invoice. A separate provincial sales tax requires its own current provincial review.
A practical accounting focus for Toronto
The local example is high transaction volume, several revenue channels, and customers in more than one province.
The decision focus is whether the monthly close is detailed enough to support HST reporting, corporate tax estimates, financing conversations, and owner decisions.
- Reconcile gross sales before payment processor fees
- Track HST using the place of supply facts
- Keep owner and corporate transactions separate
- Review payroll and contractor records before year end
Official sources
Call or email and we will tell you which records we need and what the work costs, in writing, before anything starts.
Important. This article provides general educational information, not legal or tax advice for a specific business. Rules, administrative policies, rates and deadlines can change. Confirm your facts and current obligations with the responsible government agency and a qualified adviser.