Accounting across Canada
Accounting and Tax Guide for Victoria Businesses
A practical Victoria accounting and tax guide covering records, sales tax, payroll, provincial considerations, and corporate planning.
Sources checked August 20267 min read
What the official Victoria data shows
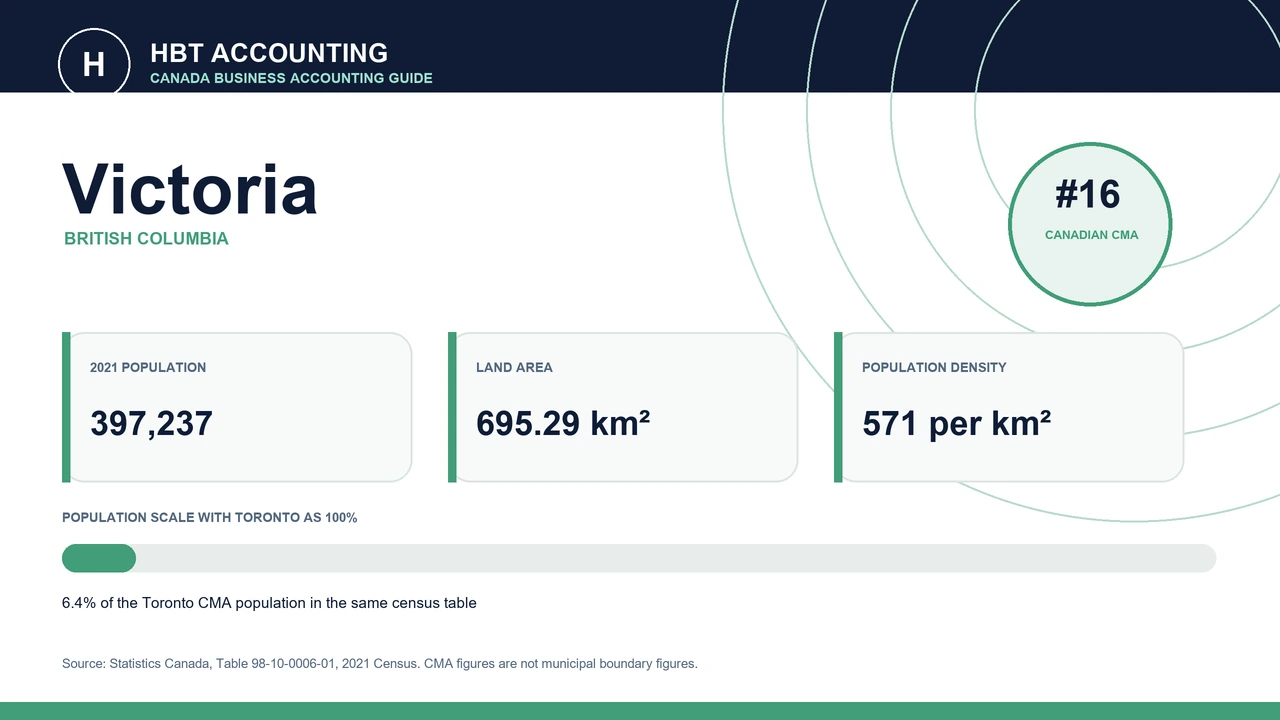
Statistics Canada ranked the Victoria census metropolitan area number 16 among Canadian census metropolitan areas by 2021 population. The official table reports 397,237 people across 695.29 square kilometres. That is about 571 people per square kilometre. The calculation uses the population and land area in the same official table.
The official population number clarifies the scope of the region. It does not replace a review of who earns the revenue, where supplies are made, who works for the business, and which accounts are registered. For Victoria, the practical planning theme in this guide is service revenue, purchased software, remote customers, and British Columbia PST classifications.
| Measure | Result | How to interpret it |
|---|---|---|
| Population | 397,237 | Census metropolitan area, not municipal boundary |
| Land area | 695.29 km2 | Land area in the same Statistics Canada table |
| Population density | 571 people per km2 | Calculated from the official population and land area |
| National CMA rank | Number 16 | Ranked by the 2021 population used for this series |
Key points
- Confirm the legal entity, registrations, reporting periods, deadlines, and responsible people before preparing a return.
- Victoria businesses may have federal GST, payroll, and income tax obligations as well as British Columbia PST requirements. The provincial treatment depends on the product or service, the place of the transaction, and current effective dates.
- Statistics Canada reported 397,237 people in the Victoria census metropolitan area in the 2021 Census. This is census metropolitan area data, not a municipal population.
- HBT Accounting works from Calgary, Alberta and can discuss suitable remote engagements across Canada. This page does not represent a Victoria office.
Build the federal and British Columbia reporting map
Victoria businesses may have federal GST, payroll, and income tax obligations as well as British Columbia PST requirements. The provincial treatment depends on the product or service, the place of the transaction, and current effective dates.
A Victoria service firm should review both what it sells and what it buys. Provincial tax can affect customer invoices, software, equipment, and self assessment obligations in different ways. The records should code sales and purchases by tax treatment, keep customer location evidence, and review recurring software invoices. For GST or HST, the applicable rate can depend on the supply and the CRA place of supply rules, not simply the city shown on the invoice. A separate provincial sales tax requires its own current provincial review.
- List every active program account beside the correct legal entity.
- Record the reporting period, filing date, payment date, preparer, and approver.
- Reconcile each tax and payroll control account to the return or remittance.
- Keep the official source and transaction evidence behind recurring tax decisions.
A practical accounting focus for Victoria
The local example is service revenue, purchased software, remote customers, and British Columbia PST classifications. This does not claim that every company in the region operates alike. It shows how broad compliance rules can be converted into a record process that reflects actual transactions.
The owner level question is Which balances affect the next filing or cash decision? In this case, the decision focus is whether the business understands the tax treatment before a new service or subscription is added. Review that question during the monthly close while contracts, invoices, payroll, and operating decisions are still familiar.
- Review tax treatment before launching a service
- Retain customer and delivery location evidence
- Check recurring software purchases
- Reconcile GST and PST in separate accounts
What to prepare before requesting accounting advice
A clean intake starts with the latest finalized records and a list of unresolved questions. Include the incorporation or registration records, prior returns, notices of assessment, current trial balance, general ledger, financial statements, bank and credit card statements, payroll reports, sales tax work, financing records, and upcoming deadlines.
HBT Accounting is physically based in Calgary. For a potential remote engagement involving Victoria, the firm must first confirm the entity, province, software, records, professional scope, timing, secure access, and capacity. Start from the Calgary contact page or call +1 (587) 894-7451. The result may be a defined engagement, a request for cleanup information, or a referral when another specialist is better placed to help.
- Use a secure document method for sensitive financial and identity records.
- Separate finalized documents from drafts and identify the reporting period.
- List open notices, late filings, uncertain balances, and time sensitive decisions.
- Agree in writing on responsibilities, information dates, deliverables, and fees.
Official sources
Call or email and we will tell you which records we need and what the work costs, in writing, before anything starts.
Important. This article provides general educational information, not legal or tax advice for a specific business. Rules, administrative policies, rates and deadlines can change. Confirm your facts and current obligations with the responsible government agency and a qualified adviser.