Research briefs
Writing Off Equipment at Once in Canada: Immediate Expensing and Faster CCA in 2026
100%of the cost of most new depreciable property could be deducted in the year it becomes available for use under the Productivity Mega Deduction the Department of Finance proposed in September 2026.
By HBT AccountingSources checked 6 min read
Key points
- The proposed Mega Deduction would allow a 100% first year deduction on most depreciable property acquired from September 15, 2026
- It is draft legislation, so property bought now is still governed by the rules in force
- Property that does not qualify keeps a larger first year deduction and no half year rule under the reaccelerated investment incentive
- A deduction starts only when the property is available for use, so delivery and installation dates near year end matter
What is proposed and what is law
In September 2026, the Department of Finance proposed the Productivity Mega Deduction. It would allow immediate expensing, meaning the full cost of eligible property is deducted in the year it becomes available for use, on a permanent basis. Finance says it would cover about two thirds of capital investment, against about 15% under the Productivity Super Deduction of Budget 2025. The estimated extra cost is $36 billion over five years.
Finance puts the marginal effective tax rate on new business investment at 6.4% after the change, against 13.0% after the Spring Economic Update 2026 and 16.9% for the United States in 2026. The proposal is draft legislation, released in September 2026 and confirmed in the federal budget tabled in November 2026. It is not law.
What is law is the Budget 2025 Implementation Act, No. 1, S.C. 2026, c. 3, which received royal assent in March 2026. Its summary says it reinstates the accelerated investment incentive and immediate expensing for certain qualifying assets. Its amendments to subsection 1100(2) of the Income Tax Regulations give Classes 44, 46 and 50 a full first year deduction for property acquired after April 15, 2024 and available for use before 2027.
The rules in force today
For property acquired after 2024 and available for use before 2034, the CRA describes the reaccelerated investment incentive. It suspends the half year rule, and for property available for use before 2030 it adds 50% of the net addition to the class before the rate is applied. Phase out begins for property available after 2029. The incentive changes the timing of deductions, not the total over the life of the property. Property acquired before 2025 can still qualify for the older accelerated investment incentive if it becomes available for use before 2028.
Certain classes already get a full first year write off. These include manufacturing and processing machinery, clean energy equipment, zero emission vehicles for a limited period, and computers, data network equipment and patents acquired after April 15, 2024 and available for use before 2027. Items under $500 in Class 12 are fully deductible in the year of purchase.
| Property type | Class and rate | First year treatment |
|---|---|---|
| Furniture, tools of $500 or more, machinery and equipment | Class 8, 20% | Reaccelerated incentive now. Full cost under the proposed Mega Deduction |
| General purpose computers and systems software | Class 50, 55% | Full write off for property acquired after April 15, 2024 and available for use before 2027. Proposed Mega Deduction after |
| Small tools and items under $500 | Class 12, 100% | Fully deductible in the year of purchase |
| Manufacturing and processing machinery | Class 53 or 43 | Full write off in the year available for use, phased out after 2029 |
| Clean energy generation equipment | Class 43.1, 30% | Full write off in the year available for use, phased out after 2029 |
| Zero emission vehicles | Classes 54, 55 and 56 | 100% if available for use before 2030, then 75%, then 55% |
| Passenger vehicles | Class 10 or 10.1, 30% | Reaccelerated incentive. Certain vehicles are excluded from the Mega Deduction |
| Buildings | Class 1, 4% | Reaccelerated incentive. Excluded from the Mega Deduction |
| Franchises, licences and goodwill | Classes 14 and 14.1 | Excluded from the Mega Deduction |
Who qualifies
Finance's backgrounder applies the proposal to taxpayers generally and does not limit it to Canadian controlled private corporations. The draft regulations give corporations, and partnerships whose members are all corporations, the full deduction. For an individual, or a partnership with individual members, the deduction cannot exceed the income earned from the business or property where the asset is used. It cannot create or increase a loss.
New property qualifies if it has not been used before. Used property qualifies only if neither the buyer nor anyone not at arm's length with the buyer owned it before, and it was not transferred on a tax deferred rollover. The draft sets no dollar limit on the deduction.
Excluded property includes certain buildings in Classes 1 and 3, Classes 14, 14.1 and 51, and certain vehicles in Classes 10 and 10.1. For vehicles, the draft names passenger vehicles that were used before purchase or assembled outside Canada. A buyer of a Class 10.1 vehicle can also elect, on the return for the year of purchase, to leave it out of immediate expensing. For vehicles bought in 2025, the Class 10.1 cost limit is $38,000 before sales tax.
Finance says manufacturing and processing buildings are outside the Mega Deduction but stay eligible for the temporary measure from Budget 2025. The CRA still labels that measure as proposed, and it is not in the Income Tax Regulations as they stand. It would allow a 100% first year deduction for buildings acquired after November 3, 2025, if at least 90% of the floor space makes goods for sale or lease. The rate falls to 75% for tax years ending in 2030 or 2031 and to 55% for tax years ending in 2032 or 2033.
An illustration with round numbers
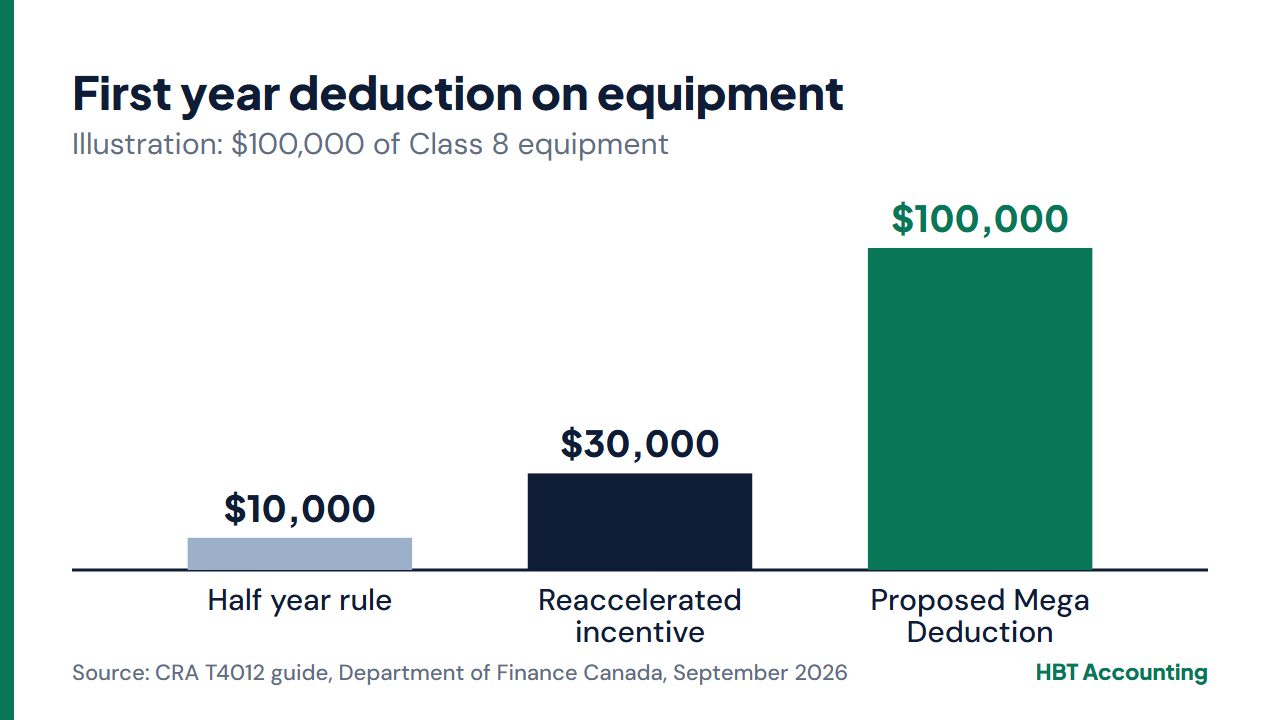
The table is an illustration only. It applies the class rate of 20% to $100,000 of Class 8 equipment that becomes available for use in its first year. It assumes an owner with enough income to use the deduction, and it ignores short tax years and provincial rules.
| Rule | How it works | First year deduction |
|---|---|---|
| Half year rule | 20% of one half of the cost | $10,000 |
| Reaccelerated investment incentive | 20% of 150% of the cost, half year rule suspended | $30,000 |
| Mega Deduction, proposed | Full cost in the year available for use | $100,000 |
Timing around the fiscal year end
Two dates matter. The first is the acquisition date. Property acquired before September 15, 2026 is outside the proposed Mega Deduction, even if it is installed later, though the reaccelerated incentive may still apply. The second is the date the property becomes available for use, because the deduction belongs to the tax year in which that happens.
For property other than a building, the CRA says that date is the earliest of four events. The first is the use of the property to earn income. The others are the second tax year after the year of acquisition, the time just before disposal, and the time it is delivered and can produce a saleable product or service. A machine delivered in December but not installed until January may therefore belong to the next year.
Buildings follow a different test, whose first event is the date 90% or more of the building is in use. The claim itself is optional, and a taxpayer can deduct any amount up to the maximum. These are federal rules, and provincial treatment of capital cost allowance should be confirmed for the province where the business files.
Quick answers
Can I write off equipment in full in the year I buy it?
Only for certain classes today, such as manufacturing machinery and items under $500. The proposed Productivity Mega Deduction would extend this to most depreciable property acquired on or after September 15, 2026, once it is enacted.
Does immediate expensing apply to used equipment?
As drafted, yes, but only if neither the buyer nor a person not at arm's length owned it before and it was not acquired on a rollover.
Can an individual or sole proprietor use the Mega Deduction?
The draft allows it, but the deduction cannot exceed the income from the business or property where the asset is used, so it cannot create a loss.
Are buildings and vehicles eligible?
Buildings in Classes 1 and 3 are excluded, as are certain vehicles in Classes 10 and 10.1. Those assets still get the reaccelerated investment incentive.
What if equipment is bought before year end but not installed?
The deduction starts when the property is available for use. For equipment that is the earliest of first use, delivery when it can produce a saleable product or service, and the second tax year after acquisition.
Related pages
Official sources
- Department of Finance Canada: Government of Canada introduces new Productivity Mega Deduction to boost Canada's advantage as the most competitive G7 country for new business investment
- Department of Finance Canada: Draft Legislative Proposals Relating to the Income Tax Act and the Income Tax Regulations
- CRA: Classes of depreciable property
- CRA: T2 Corporation - Income Tax Guide - Chapter 3: Page 3 of the T2 return
- CRA: T2 Corporation - Income Tax Guide - What's New
- CRA: How to calculate the deduction for capital cost allowance (CCA)
- Justice Laws: Budget 2025 Implementation Act, No. 1, S.C. 2026, c. 3
Call or email and we will tell you which records we need and what the work costs, in writing, before anything starts.
Important. This article provides general educational information, not legal or tax advice for a specific business. Rules, administrative policies, rates and deadlines can change. Confirm your facts and current obligations with the responsible government agency and a qualified adviser.