Industry tax guides
Construction Contractor Taxes in Canada: Holdbacks, T5018 and GST
Holdbacksare not GST/HST payable until they are paid out or required to be paid out, which is often months after the progress billing they came from.
Sources checked October 20263 min read
Progress billings and holdbacks for income tax
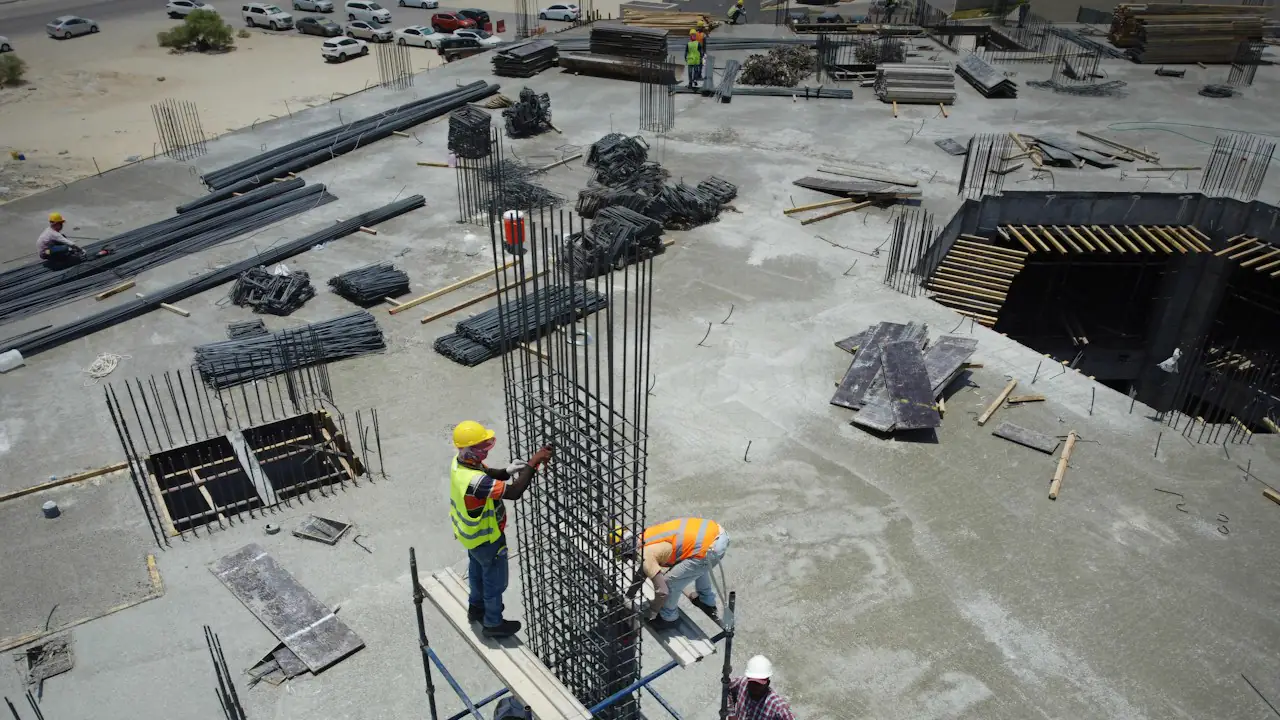
Construction contracts usually bill in stages, and provincial lien legislation or the contract itself often requires the owner to hold back part of each payment until the job is finished. The CRA's long standing position, set out in its archived bulletin on contractors' income, is that a progress billing less the holdback becomes income when the owner or the owner's architect or engineer approves it for payment. The holdbacks become income on the later of the day the final certificate of completion is issued and the day the lien period expires.
Any amount actually received is income when received, even if it should have been held back. Where a contract does not require formal approval, a billing net of holdback is income when it is issued. A contractor can choose to report all billed amounts, holdbacks included, as long as it does so consistently.
Key points
- Progress billings are income when approved for payment, less any holdback
- Holdbacks become income later, generally when the job is certified complete and the lien period has expired
- GST/HST on a holdback is due when it is paid out or required to be
- Contractors who pay subcontractors for construction services file T5018 slips
GST/HST on billings and holdbacks
GST/HST on a progress billing is generally owed in the reporting period the invoice is issued, whether or not the owner has paid. Holdbacks are the exception: where part of the price is retained under federal or provincial law, or a written construction agreement, pending satisfactory completion, no tax is payable on the holdback until the day it is paid out or required to be paid out, whichever is earlier. Tracking holdbacks receivable separately keeps both the income and the GST/HST right.
Subcontractors, slips and crews
A business whose main activity is construction reports payments to subcontractors for construction services on T5018 slips, and each subcontractor relationship should be checked against the employee or contractor tests before the first payment. Meals provided to employees housed at a temporary work camp built to feed and house workers at a construction site are not subject to the 50% meal limit.
Employed tradespeople who relocate temporarily for construction work may claim the labour mobility deduction on their own returns, which the tradesperson deductions guide explains.
Quick answers
When is a construction holdback taxable income?
Under the CRA's long standing position, on the later of the day the final certificate of completion is issued and the day the provincial lien period expires, unless the contractor consistently reports all billings, holdbacks included, as they are issued.
Do I charge GST on a holdback when I invoice?
The holdback is part of the price, but the GST/HST on it is not payable until the holdback is paid out or required to be paid out, whichever comes first.
Who has to file T5018 slips?
A business whose main activity is construction that pays subcontractors for construction services. The T5018 guide covers the details and deadlines.
Related pages
Official sources
Call or email and we will tell you which records we need and what the work costs, in writing, before anything starts.
Important. This article provides general educational information, not legal or tax advice for a specific business. Rules, administrative policies, rates and deadlines can change. Confirm your facts and current obligations with the responsible government agency and a qualified adviser.